Generali Central

How much health insurance do you need?

With the growing healthcare costs and increasing medical vulnerabilities, having health insurance is a must. But the real question is – how much health insurance do you need? Well, we can help you find the correct health insurance cover, with which you can lead a worry-free life.
Does your policy actually protect you in times of need?

A medical emergency can happen any time, without warning. Does your health insurance actually reduce the intensity of the blow? Or does it fail to protect you when you need it the most?

You can be rightly insured, over insured, or underinsured. The right insurance coverage depends on your age, health condition, and lifestyle. When you're rightly insured, your cover pays for all your medical expenses. When you're over insured, your insurance cover is more than what you need. Such a policy will be expensive. But there’s nothing worse than being underinsured.

Underinsured

What does being underinsured mean?

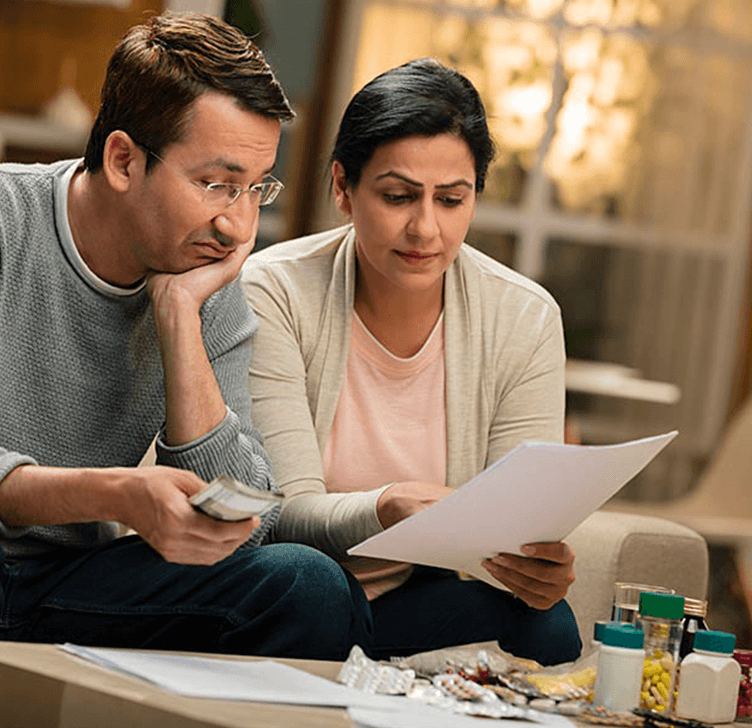
Having health insurance coverage is the need of the hour. But, for many people, the process of buying insurance ends when they pay the premium.

Underinsurance is when your policy doesn't offer you enough coverage to manage medical emergencies. Most people realise this at the time of making a claim. In such scenarios, being underinsured is much like being uninsured.

This is what underinsurance looks like

You have a health insurance cover enough to cover any major illnesses. But, as time passes and inflation kicks in, your insurance cover loses its value. When the need arises, you find your insurance cover lacking. to give you an idea, below are some of the most common ailments & their treatment costs.

ONCOLOGY (CANCER) TREATMENT

ONCOLOGY
(CANCER)
TREATMENT

Chemotheraphy (per cycle)

₹12.7 lakh -

₹14.6 lakh

Breast Cancer Surgery

₹ 1.9 lakh -

₹ 4.25 lakh

Prostrate Cancer Surgery

₹ 3.49 lakh -

₹ 6.35 lakh

NEURO SCIENCE

NEURO
SCIENCE

Deep Brain Stimulation (for Parkinson's)

₹ 63,500 -

₹ 1.9 lakh

Breast Cancer Surgery

₹ 1.9 lakh -

₹ 4.25 lakh

CARDIOLOGY/ CARDIOTHORACIC SURGERY

CARDIOLOGY/
CARDIOTHORACIC
SURGERY

Angioplasty (one stent)

₹ 1.9 lakh -

₹ 4.12 lakh

Bypass Surgery (CABG-coronary artery bypass graft)

₹ 1.9 lakh -

₹ 6.03 lakh

Congenital Heart Defects (ASD/VSD Closure)

₹ 1.9 lakh -

₹ 6.35 lakh

Valve Replacement AVR/MVR (including valves)

₹ 3.81 lakh -

₹ 7.62 lakh

Valve Replacement AVR/MVR (minimal invasive procedure)

₹ 1.9 lakh -

₹ 6.03 lakh

TRANSPLANT

TRANSPLANT

Heart Transplant

₹ 14.6 lakh -

₹ 25.4 lakh

Liver Transplant

₹ 25.4 lakh -

₹ 35.97 lakh

Kidney Transplant

₹ 3.17 lakh -

₹ 13.97 lakh

Lung Transplant

₹ 13.97 lakh -

₹ 15.87 lakh

Think you don't need health insurance? Think Again!

From cancer and cardiological ailments to organ transplants and neurological treatment, the costs of these procedures today are through the roof. Take a look yourself.

2015

Number of cancer patients over 8,00,000

2023

rose to 19,58,310

Expensive Surgeries & Procedures

Head & Neck Cancer Surgery

₹2 Lakh

IMRT
(Cancer Stage 2)

₹1.5 Lakh

Chemotherapy

₹90,000

Average Cost for Cancer Treatment

₹1,65,680

Expensive Medicines for Cancer

Herceptin
(Breast Cancer)

₹75,000 to
₹1,00,000/ vial

Zytiga
(Prostate Cancer)

₹1,50,000

Avastin (Kidney & Colon Cancer)

₹25,000 to
₹50,000/ cycle

Erleva (errloxinio) by Roche (Lung Cancer)

₹1,20,000

Erbitux (Head & Neck Cancers)

₹1,00,000/ cycle

Rituximab (Leukaemia)

₹50,000/ cycle

Spryccel 50mg 50 tablets (Blood Cancer)

₹1,65,680

How do I avoid being underinsured?

Here are some steps to avoid being underinsured:

Do your homework

To avoid any nasty surprises down the road, do proper research before buying a policy. Go through the exclusions and inclusions carefully, and make sure that you understand the fine print.

Assess your needs carefully

Remember that a few years down the line, your health won't be the same. Also, there's inflation to consider. So, factor all these parameters in while making an insurance decision.

Select the right insurance amount

When choosing a plan, select the insurance amount wisely as it'll cover your medical expenses for a year. Consider your age; the younger you are, the lower the sum insured you need. You should also take a look at your income levels to analyse how much premium you can afford.

Premium payment capacity

When it comes to health insurance, it’s best to pay what you can afford. As a rule of thumb, set aside 2% of your annual income for insurance premium. So, if you earn Rs. 5 lakh in a year, spend Rs. 10,000 towards policy premium.

Percentage of annual income

When choosing a policy, make sure the sum insured lies between 50% and 100% of your annual income.

Family medical history

Insurance providers also look at your and your family's past medical encounters when deciding your insurance cover. Members falling under the high-risk category may require a comprehensive health cover, which comes at higher premiums.

Type of hospital

No two hospitals are made equal. Choose the best hospital according to your cover and needs when buying a policy.

Age

When it comes to health insurance, the lower your age, the lower your premium. For instance, if you're 25 years of age, you'd have to pay just 6,000 a year for a Rs. 10 lakh cover. A person aged 45 years would need to pay Rs. 20,000 to get the same cover.

Tax benefit

If you’re purchasing insurance primarily for the tax benefits, you don’t need a comprehensive plan. Remember that the maximum tax deduction limit is Rs. 25,000. For senior citizens, it’s Rs. 30,000.